
Every market has a physics. A structural logic that determines how things get found, how choices get made, and where value collects. Most of the time this logic is invisible. Not because it’s ‘natural,’ but because it’s settled and nobody questions it. The interesting moments are when the physics changes.
It happened when broadcast media assembled mass audiences and markets organized around the average. Whole industries, careers, and ways of life were built on the assumption that being relevant for the mainstream was the safest strategy. Until it wasn’t.
It happened again, when networked platforms rewired distribution and markets reorganized around extremes. This shift took about a decade to become fully legible. Attention became the currency, algorithms became the gatekeepers, and a new brutal logic took hold: if you weren’t the most at something, you were nothing at all.
And it is happening now. This latest one is arriving faster, because the forces driving it are compounding on each other. Agentic software that makes decisions on behalf of humans, and a new kind of neural media that doesn’t just distribute content but generates it, senses its audience, and adapts in real time.
When the physics shifts, the experience on the ground is disorientation. Brand and growth strategies that worked stop working and articulating why is tricky. Many discover they’re well-trained for a game that is no longer played.
Understanding the shifting physics, the version that’s fading and the version that’s forming, is now a survival question for any brand or business that expects to be leading in their game and still be competing in the coming years.
What follows is a map of how three media eras (broadcast, network, neural) rewired the rules of competition, and what it takes to thrive inside the new physics that’s replacing the one you built for.
Markets are matching problems
The physics of a market is set by how it organizes attention, choice, and value. This sounds abstract until you think about what a market actually does. Strip away the products, the branding, the experience, the supply chains, the pricing strategies, and what remains is a matching problem. People and organizations have needs. Others have capabilities, remedies, and offerings. The market is whatever system connects these together. How that system captures attention, how it structures choice, and where it lets value emerge determines everything downstream. What gets found and what disappears. Where the money pools and where it drains. Change it and you change the shape of competition.
This was always true, but for most of commercial history the matching function changed slowly enough that it looked like a fixed condition. You could build a career, a company, a whole industry on the assumption that the way things get found and chosen would remain stable. And for long stretches, it did.
What makes the current moment vertiginous is that the matching function has seen major turns in a relatively short time, all layered up, speeding to alternate directions depending on the business category and market segment.
Each time the physics changed, it produced a different distribution of outcomes, created new winners from unexpected places, and made previously safe positions suddenly fragile.
The broadcast era: the physics of the average
For the better part of the twentieth century, the dominant media were broadcast. One signal, many receivers. A radio tower, a television network, a newspaper with national distribution. The spatial logic was centralized: content originated from a small number of sources and radiated outward to a mass audience that had limited ability to talk back or route around it.
This architecture produced a specific matching function. Because reaching an audience meant paying for access to the whole audience, the economics favored messages that worked for the largest possible share of it. You couldn’t target the left-handed fly fishermen. You got everybody or nobody, so you aimed for the middle.
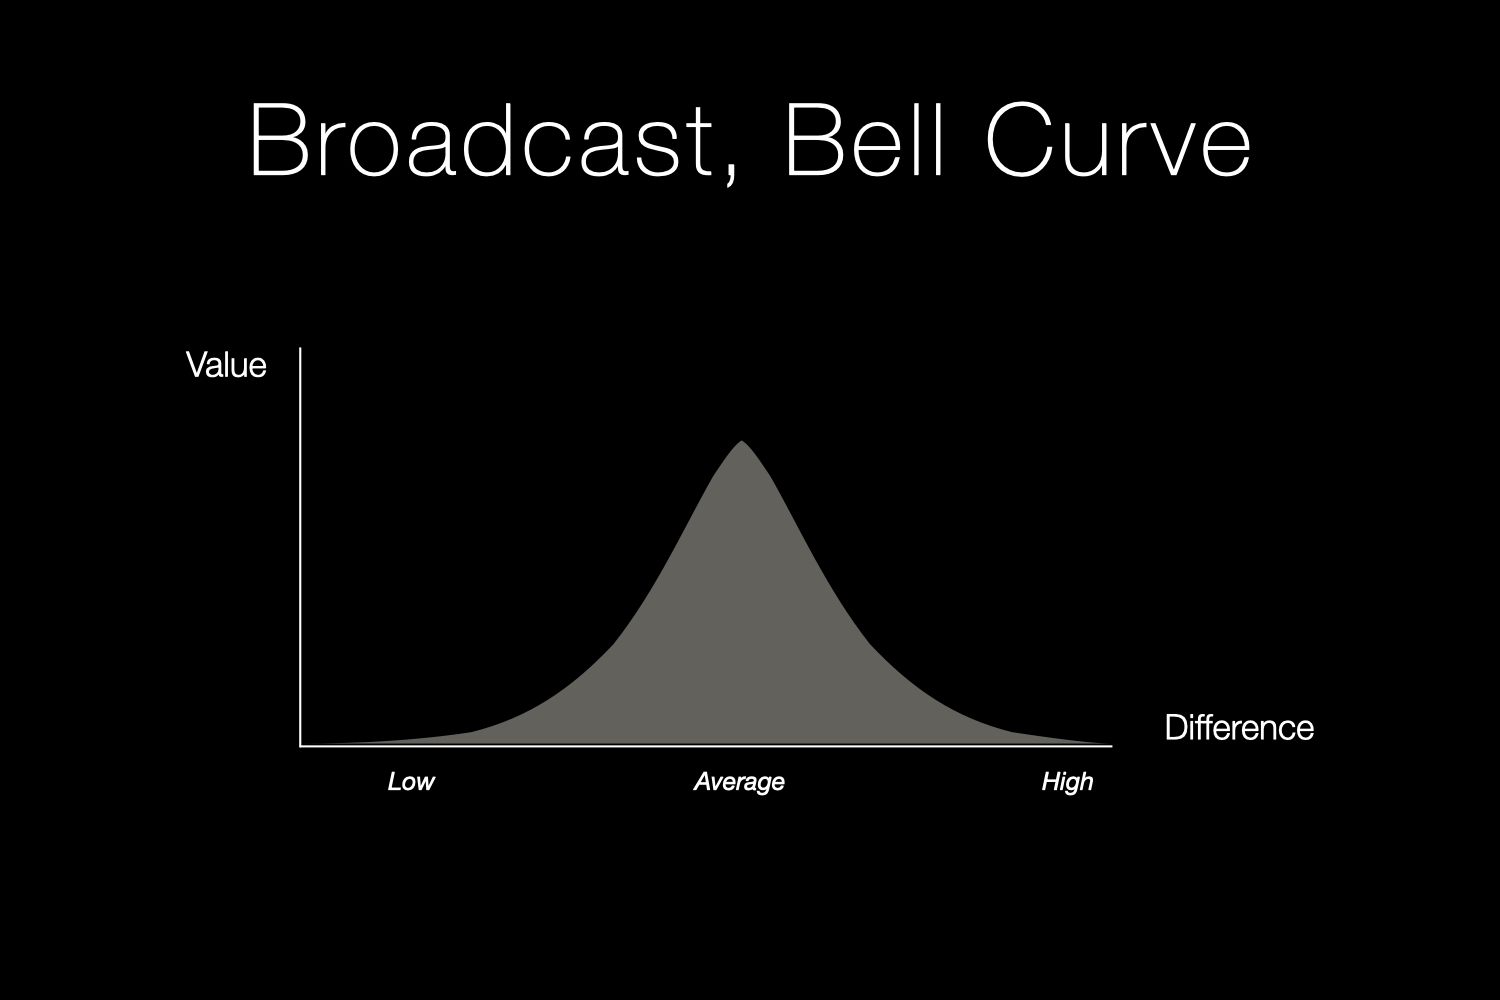
The market that resulted was a bell curve. Most demand clustered around the center, because the physics of broadcast made the center the easiest thing to find and the hardest thing to avoid. Products that were reasonably priced, reasonably well made, and reasonably widely known dominated, because the system was structurally incapable of connecting niche offerings to niche needs at any kind of scale. The extremes existed, but they were expensive to reach and hard to sustain.
The subject this architecture produced was the demographic. Broadcast couldn’t see individuals. It saw age brackets, income bands, gender categories, metro areas. You were not a person with particular tastes. You were a 35-to-54-year-old man in a mid-income household. Your preferences were assumed to be roughly average, because the system had no way to discover that they weren’t.
Towards the end of the century, the savvier brands learned to cheat this logic a little. Calvin Klein sold aspiration and provocation rather than category membership, but even that was a broadcast move: a single image projected at millions, hoping enough of them felt seen. The controversy was the media buy.
The strategic implications were clear and for a long time they were correct. Differentiation in general was risky. Real eccentricity was expensive. The mainstream winning move was to find the center, hold it, and scale. Build the brand that offended nobody and appealed to everyone.
The mass brand was the native entity of this era, and it worked because the physics of broadcast rewarded exactly what it was good at: consistent, moderate, familiar, everywhere.
This is the physics that most legacy brands and businesses were built on. Many are still running it, even the ones that think they’ve moved on.
The network era: the physics of extremes
Around the turn of the millennium, the architecture started to change. The internet replaced the spatial logic entirely. Broadcast was centralized, one to many. Networks were circulatory, many to many. Every node can publish, share, amplify, or ignore. Distribution was something that emerged from the behavior of the network itself.
The matching function that followed was preferential attachment. In a network, the visible become more visible. The popular attract more attention, which makes them more popular, which attracts more attention. Small early advantages in timing or positioning compound into enormous differences in outcome. The mathematics here are well understood and brutal: networks do not converge toward an average. They concentrate around a small number of winners and distribute the rest across a long tail that stretches out toward zero.
The market distribution that resulted was not one power law but several, running simultaneously across different categories. A tiny fraction of musicians captured the vast majority of Spotify streams. A handful of YouTube channels absorbed most of the views. A few apps generated nearly all the revenue in the app stores. In attention markets, preferential attachment concentrated value around signal and virality. In commodity markets, a parallel power law concentrated value around cost efficiency and scale.
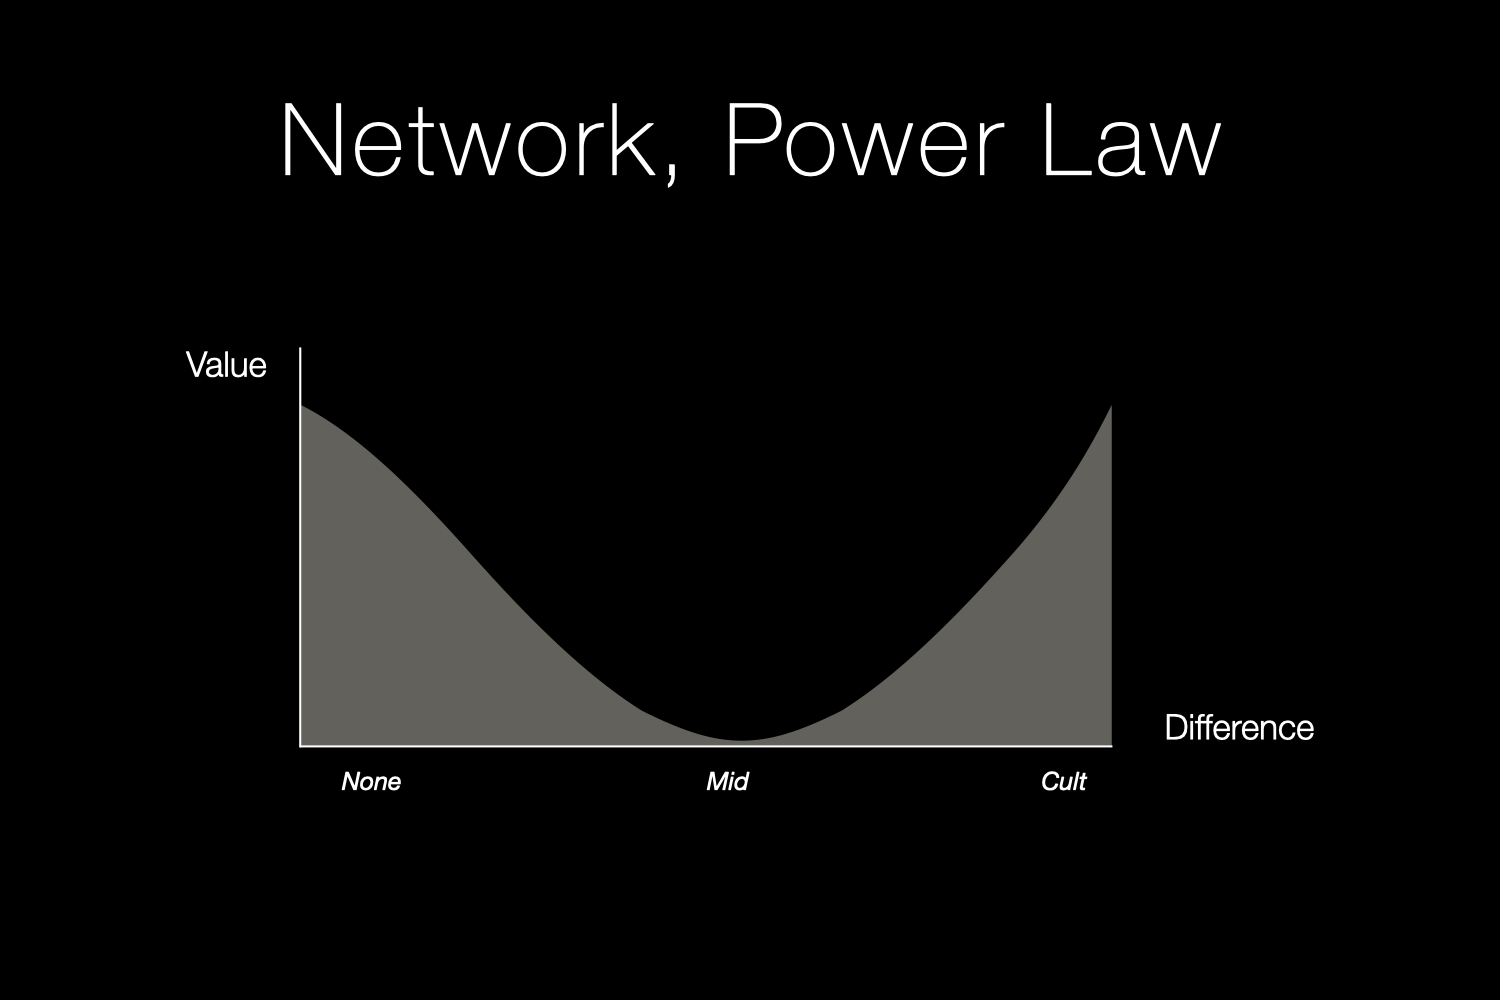
Different mechanics, same structural outcome: the bell curve inverted. The center, that safe, lucrative plateau where mainstream relevance had been enough, hollowed out. And value concentrated at both ends of the spectrum: on one side, cult brands and superlative positions, signal-rich entities that the network amplified. On the other, white label, commodity, price-dominant players that won through cost, scale, and logistics. Grocery store own-brands, ultra-fast fashion, Amazon Basics. These aren’t distinctive at all, but “most cheap” is still most at something.
The middle became something worse than unprofitable. It became mid. Mid meant you generated no signal. You weren’t bad enough to be memorable or good enough to be chosen. You produced no spike in attention, no compelling reason to pick you over the alternatives, no emotional charge strong enough for the algorithm to grab onto and amplify. In a world where feeds are optimization machines tuned to arousal, mid was the valley floor. Worse than bad, because bad at least gets reposted. Mid gets scrolled past.
The subject this architecture produced is fractal. Where broadcast had sorted people into a handful of demographic boxes, networks shattered identity into a thousand micro-affiliations. Subcultures, fandoms, ideological niches, aesthetic tribes, your niche Discord, the specific corner of TikTok. The political compass meme, as K Allado-McDowell has noted, became a kind of game board for organizing these splintered identities. You were no longer a demographic, but a constellation of micro-positions, shifting and recombining in real time, each carrying its own codes, aesthetics, and signals. You followed Supreme drops through your feed, tracked your rides on Strava, participated in a few tightly bounded communities, adopted and discarded references as you moved.
The strategic response was to get to the tip of the power law, or get specific. Own a category at massive scale with network effects and capital moats, or own a niche with such clarity that the network does your distribution for you. Be the most at something. Most cheap, most weird, most obnoxious, most luxurious. The particular dimension matters less than the commitment to it. Superlative positions create spikes in perception, and spikes were what the network rewarded.
The cult brand was the native entity of this era. Not the mass brand trying to please everyone, but the brand that a small number of people loved more than anything. The brand that understood, consciously or intuitively, that in a power law market the only defensible positions are the extreme ones.
This is the physics most forward-thinking brands and businesses are running today. And it is already being replaced.
The neural era: the physics of legibility
The transition now underway hits different. Two things are happening at once and they are easy to confuse.
The first is agentic. Software that acts on behalf of humans is starting to handle market decisions that humans used to handle badly, lazily, or not at all. Comparing prices across platforms. Re-shopping insurance at renewal. Evaluating whether a subscription is worth what it costs. Canceling the gym membership you forgot about for eleven months. These are tasks most people knew they should do and never did, because the cognitive effort wasn’t worth the likely saving. Agents don’t experience cognitive effort. They will do the tedious thing every time, at zero marginal cost, without complaint.
Citrini Research, whose scenario briefly moved equity markets earlier this year, explained the mechanism: what agents dissolve is habitual intermediation, the rent-extraction layer that service economies built on top of human cognitive limits. Brand familiarity substituting for diligence. Checkout friction substituting for competitive advantage. The customer’s exhaustion mistaken for loyalty. When the agent removes the friction, the loyalty reveals itself as something that was never really there. Nemesis, responding to the Citrini piece, went further, arguing that as brand value drains from the products and services being transacted, it reappears upstream at the agent layer, and the relationship that matters becomes the one between you and your intermediary. This piece builds on that insight but extends it in a different direction: what happens to the brands that aren’t built on friction?
The second force is what Allado-McDowell has called neural media, and its properties are different in kind.
For the past fifteen years the dominant architecture has been network media: circulatory, memetic, powered by humans acting as nodes pushing content through feeds. Neural media don’t just distribute but also generate. They model their audience in high-dimensional space and reflect those models back in ways that reshape preferences in real time. The system senses you. It builds a representation of who you are, what you want, how you respond, and it adjusts what it surfaces based on that representation. Which changes your behavior. Which updates the model. Which changes what you see next.
When you watch your For You page teach you to want things you didn’t know you wanted, or wouldn’t have admitted you wanted, you get this intuitively. Recommendation algorithms, now charged with AI, have moved from sorting content to shaping what gets made, what gets shown, and who you become as a consumer.
This changes what a market is. In the broadcast and network eras, markets connected existing supply to existing demand. The consumer arrived with preferences and the market tried to match them. In the neural era, the market participates in forming the preferences it then serves. The consumer and the system are co-producing each other.
Each media architecture, as Allado-McDowell argues, produces a different kind of human subject. Broadcast produced the demographic. Networks produced the fractured micro-identity. Neural media are producing the embedded self, a consumer whose desires, taste, and worldview are continuously shaped by the systems that claim to merely reflect them. You didn’t choose cottagecore. The algorithm chose it for you, and only then you chose it. In the neural era, identity is becoming something like atmosphere, a continuous, ambient process of personal transformation and preference formation co-produced by the systems you inhabit.
The agentic and neural forces are entangled. The agent that finds things for you feeds from the same model that is shaping what you want. Discovery and identity formation run simultaneously, changing each other, which is what makes the neural era’s matching function a genuinely new kind of mechanism.
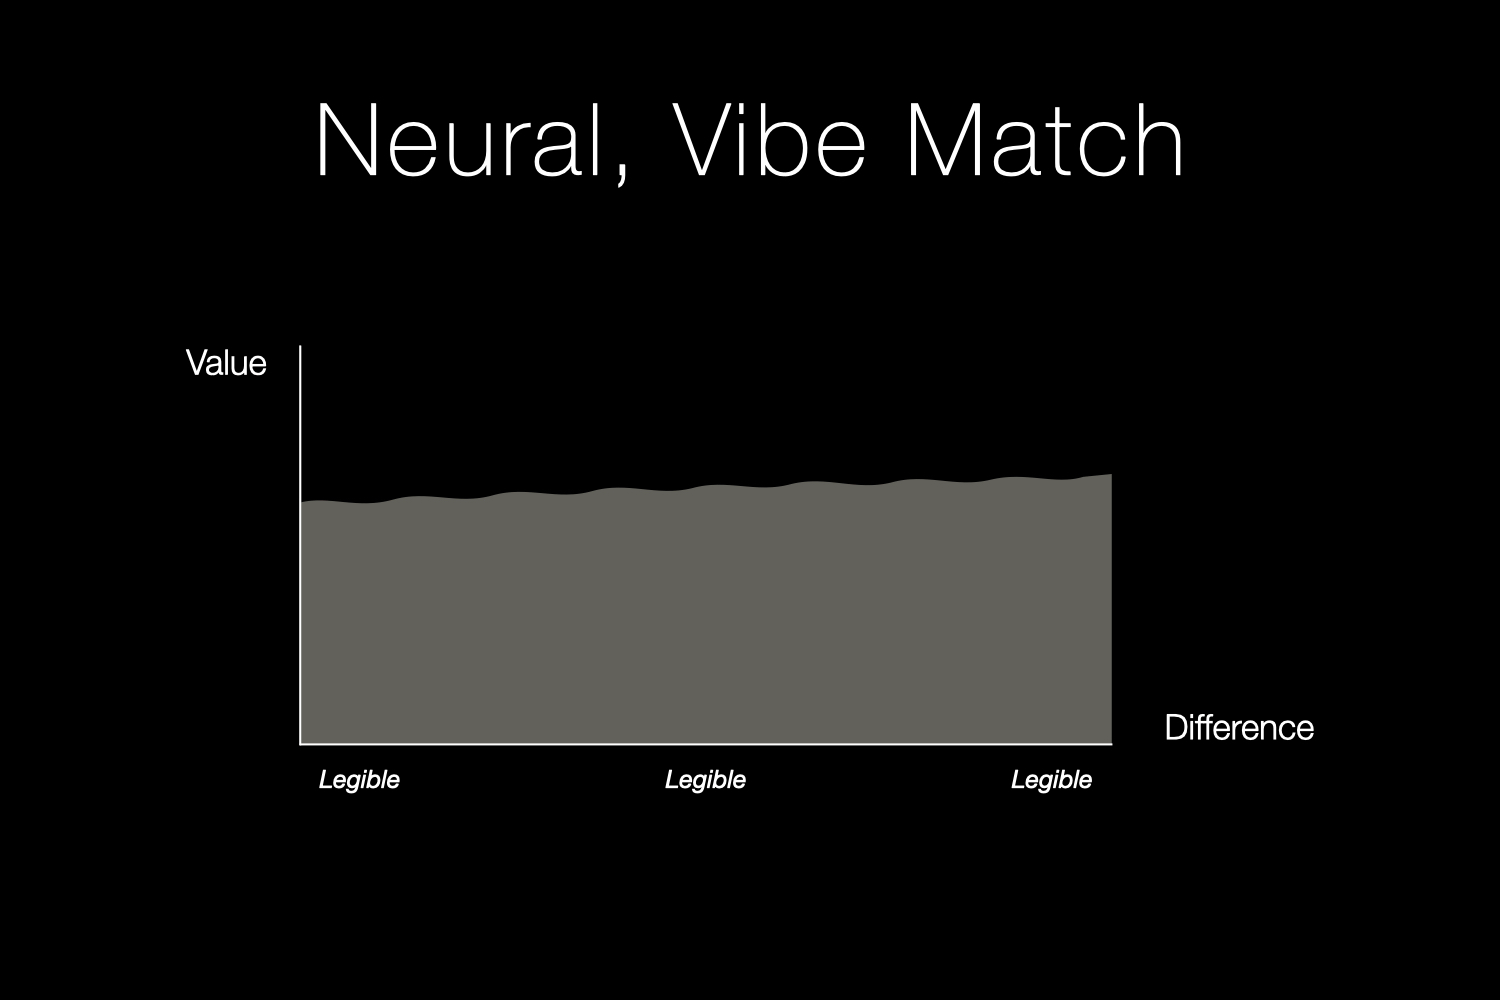
In a neural market, matching runs on semantic proximity, or what might even be called a vibe match. Not how loud a brand is, but how deeply it resonates with continuously emergent preferences, how clearly it can articulate what it offers and why it matters in this moment, and how precisely the systems doing the finding can place it among everything else.
The distribution this produces has a legibility floor. If an offering can be accurately read by the agentic and neural systems that increasingly mediate discovery, it has the potential to surface to the right people at the right time with remarkable precision. If it can’t, it doesn’t fade gradually the way a mid product did in the network era, but it vanishes from the space where matching happens, and becomes unreadable and invisible.
And unlike the broadcast-to-network transition, which took a decade to become legible, this one is moving on a compressed timeline. The agentic layer is already live and neural recommendation is reshaping retail and media. This is the market physics that is arriving now, and that brands and businesses should be building for.
Where the new digital physics hits hardest
One necessary notion before going further. The three media and market eras described above are not a sequence where each simply replaces the last. They are layers that are all running at the same time.
Broadcast didn’t disappear when networks arrived. Network logic won’t disappear as the agentic-neural layer matures. Right now, most brands and businesses are operating under all three physics simultaneously across different parts of their business and different phases of their customer relationships. The TV spot is still running while interns are posting reels while customers are asking Claude what to buy. This is a media and market geology, where each layer has its own matching function, its own distributional pressures, its own logic of what wins and what fails.
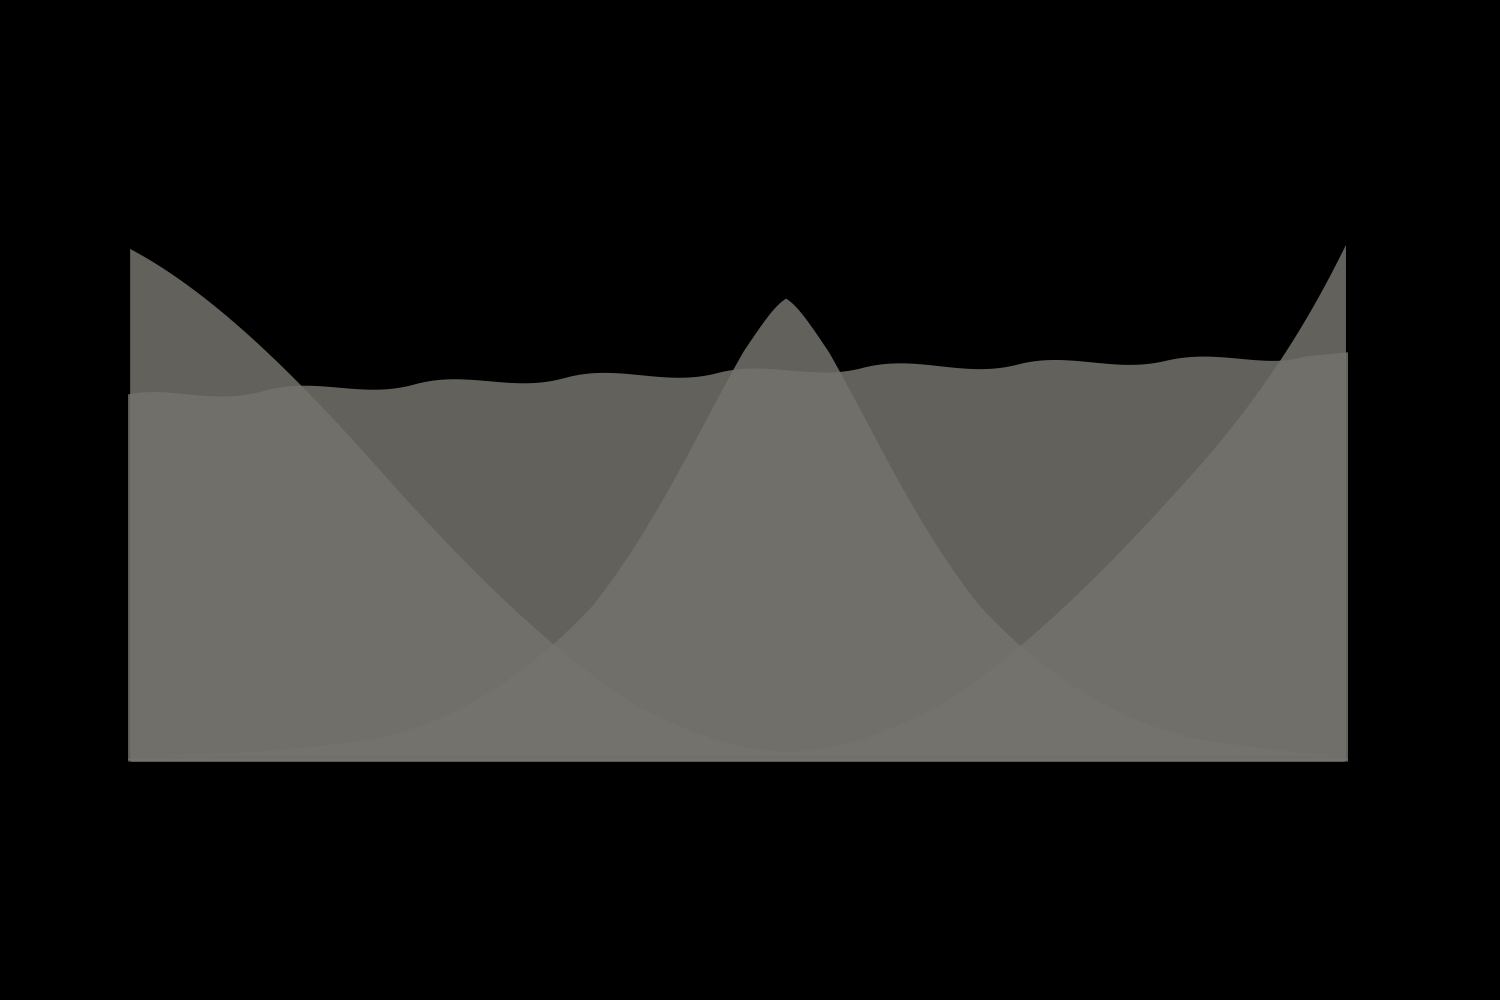
Which layer dominates depends on the category. The dominant one is whichever currently controls how supply and demand actually find each other. In travel, that used to be the travel agent, then the search result, and now increasingly the AI agent that books the journey before you’ve finished describing what you want. When the matching functions starts to shift, a new layer takes the weight.
Transition moments matter more than the stable periods between them, because during a transition the physics is still being written. The window to influence what gets written and how to translate that into success is open. Once the physics settles, competition moves inside it and the rules become given. Those that understood this during the broadcast-to-network shift were the ones that built the platforms everyone else ended up competing on, and the businesses that thrived in that competition.
The same dynamic is playing out again, faster, and with higher stakes. To make sense of this, it helps to think about where market value actually lives in different categories and for any given brand or business.
Three levels of value matter. Discovery is how offerings and people find each other, through advertising, search, feeds, recommendations, or agents. Experience is what happens when they meet, the quality of the product, the depth of the service, the texture of the encounter. Identity is the highest level: does the brand or business participate in shaping how someone sees themselves and lives their life?
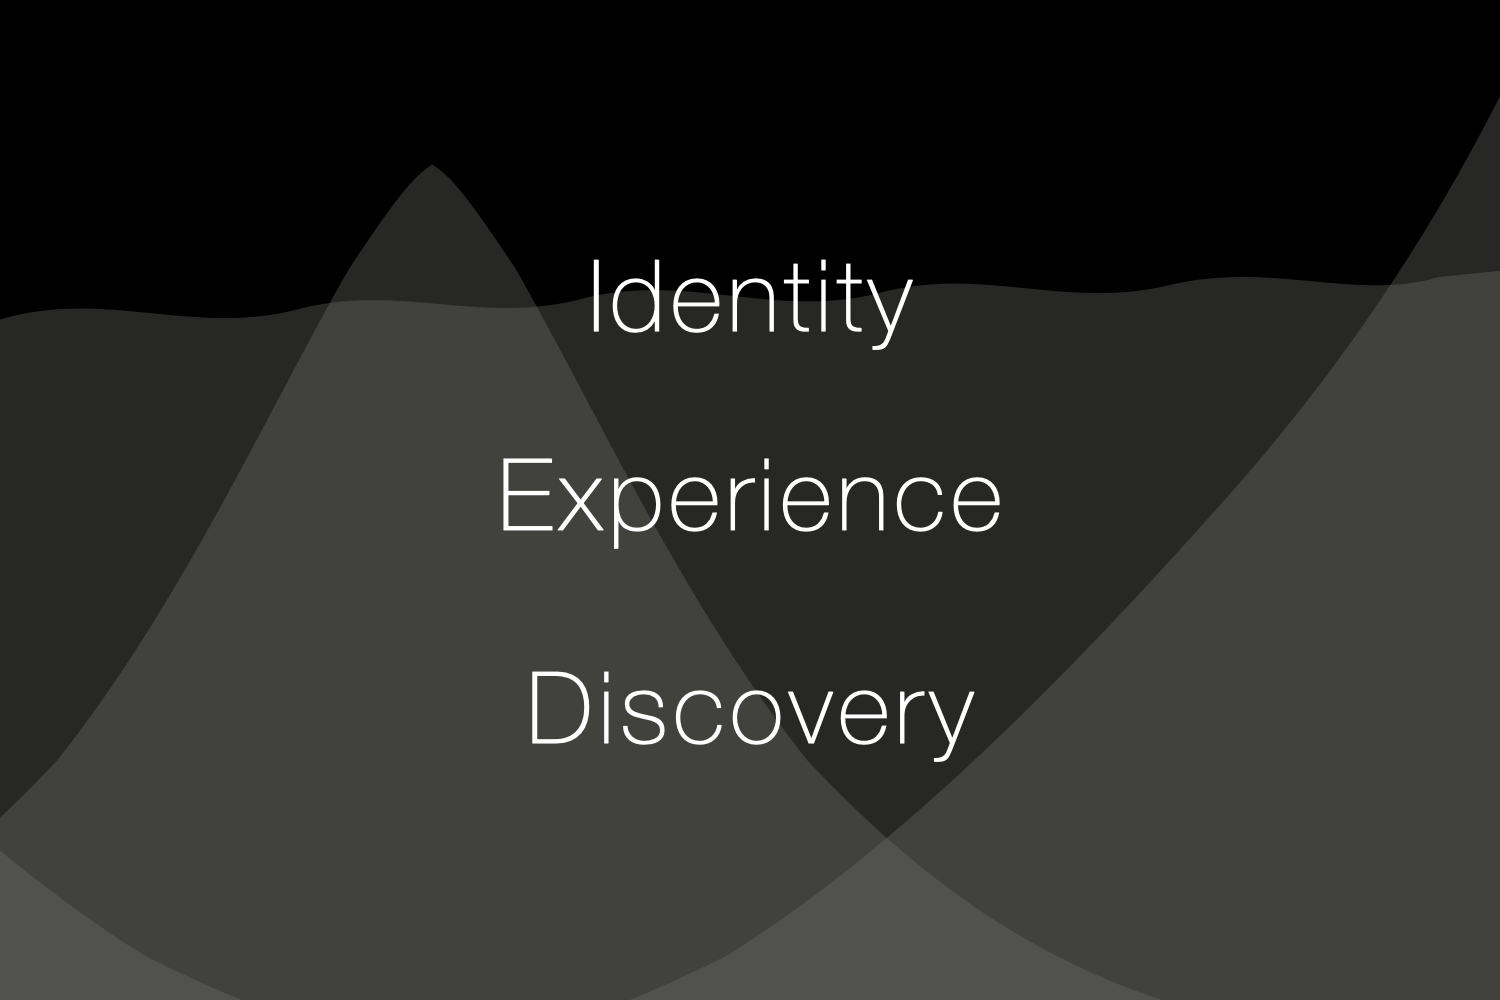
The three levels apply everywhere but they don’t hit everywhere equally. Getting the diagnosis right, knowing which level holds your value and which level is exposed, is the difference between a strategy that addresses the real threat and one that optimizes for the wrong problem.
Some categories are built almost entirely on friction. Insurance, telecom, energy, generic financial services, commodity SaaS. These are the sectors where Citrini’s habitual intermediation analysis and Nemesis’ synthesis hit hardest. At the discovery level, the moat was the whole business: the customer stayed because switching was annoying, not because the offering was better. At the experience level, there is almost nothing to fall back on, because nobody ever loved their energy provider. At the identity level, the relationship barely exists as these brands occupy no meaningful place in how people understand themselves or want to live. The agentic-neural disruption is existential here precisely because the only level where value was captured, discovery through friction, is the level most exposed. When an agent working from a model of the consumer’s actual needs re-shops, re-prices, and re-routes on their behalf, the moat drains. The strategic options are stark: build your own agentic interface so customers stay within your system, the way some banks are building AI financial advisors; accept commoditization and compete on being the cheapest, most reliable pipe that other people’s agents route through; or watch the margin disappear.
Other categories are structurally protected in ways that the agentic-neural system cannot touch. Live performance, physical care, craft, shared embodied experience, anything where presence is the product. At the experience level, these categories are safe: a neural system can optimize how you discover a restaurant, a concert, a therapist, a handmade ceramic, but it cannot eat the meal, attend the show, hold the session, or feel the glaze. At the identity level, many of these categories already run deep. A yoga practice, a favorite restaurant, a long relationship with a craftsperson can be genuinely constitutive of how someone lives. The main vulnerability is at the discovery level. The depth often already exists but hasn’t been made legible. Many of the most extraordinary experiences in the world are semantically invisible, described in language so generic or so insider-coded that the matching systems can’t place them. A master ceramicist whose website says “handmade pottery inspired by nature” is competing for attention with ten thousand other listings using the same words. The work is unmistakable in person. It is indistinguishable in embedding space. For irreducibly human categories, semantic legibility is the bottleneck, and solving it unlocks a matching system that is extraordinarily good at routing the right people to the right experiences.
A third category operates deeply across all three levels. Fashion, design, cultural institutions, media, professional services where creativity and genuine judgment sits at the core. These are meaning-heavy categories, and they face three distinct vulnerabilities simultaneously. They are exposed at the discovery level if they are semantically vague. They are resilient at the experience level only if they have built genuine cultural gravity, profound narratives and lasting outcomes. And they thrive at the identity level only if they have developed the kind of relationship with their audience where the brand participates in shaping how people live, not just what they buy.
And then there are the categories writing the physics itself. The AI companies building the models and the neural logic of discovery. The platforms laying the infrastructure that determines what gets seen, what gets matched, and what gets through. These are the physics-setters.
But the most consequential new category, and the focus here, is the one building on top of both: the rapidly growing AI-driven service businesses that don’t control the matching functions or own the infrastructure, but operate closer to them than anyone else. They use the models as engines and live inside the embedding spaces others built. Their products are assembled from capabilities they don’t own, distributed through channels they don’t control, discovered through logics they didn’t write. Which makes the three-level diagnostic both more urgent and more clarifying for them than for anyone else. At the discovery level, they face intense competition for legibility in a crowded and fast-moving field where most offerings are indistinguishable. At the experience level, the gap between demo and daily use is where most of them die. At the identity level, the winners are the ones whose tools become part of how people work, think, and create, embedded so deeply in someone’s practice that switching feels like losing a collaborator, not canceling a subscription.
This is where the strategic question sharpens. What does the native entity of the neural era actually look like in practice?
Brands built for the vibe match
The core design challenge of the neural era is building a brand that is simultaneously legible at the discovery level, deep at the experience level, and significant at the identity level.
When an agent finds something on your behalf, it is working from a model of you, your preferences, your patterns, your identity as the neural systems understand it. The human and the agent are co-navigating. Even the discovery is shaped by who you are, and who you are is being shaped by what the systems surface. The simple use case, find me the cheapest flight, is the least interesting version of this and probably the most temporary. The more significant version is an agent that matches on semantic proximity to your actual life, values, and aspirations.
And this works across the full spectrum. An agent is just as good at matching a consumer’s obsessive preference for a specific Japanese denim as their perfectly mid preference for a reliable white t-shirt. It can handle the cost-driven grocery run and the identity-driven search for the right therapist in the same session. The network era forced brands to pick an extreme because the middle was invisible. The neural era doesn’t care where a brand sits on the distinctiveness axis. It cares whether the preference and the offering are both legible enough to make the connection. Every desire, every need, how extreme or mid it might be, can have a market of its own.
This changes what a brand needs to be. A brand that describes itself in soft aspirational language may be perfectly comprehensible on a billboard and completely invisible to a model trying to place it in semantic space. Vagueness used to be a feature, a way of casting the widest net. In the neural era it is a structural disability. The matching systems that increasingly mediate discovery need something specific to work with. They need to know exactly what you are, who you are for, when you matter, and what makes you special, with enough precision that they can locate you accurately in the space where all offerings are compared. You can’t be found if you can’t be read.
But legibility solves only the discovery level. The harder question is what people find when they get there.
In a market where discovery is automated and switching is frictionless, the durable advantage belongs to the brands that have built something worth arriving at. Craft, point of view, accumulated meaning, the weight of decisions made with care over time. This is what makes someone stay when leaving has never been easier. It is the opposite of slop. And it feeds back into the discovery level, because a brand with genuine depth generates richer, more specific semantic material for the systems to work with.
Cultural depth produces the kind of legibility that positioning decks never can. Fashion brands, trying to remain relevant, are opening gallery spaces, residency programs, and restaurants alongside their retail, building worlds you can inhabit rather than a store you can visit. These are brands that have made themselves semantically unmistakable and experientially deep at the same time, because the two reinforce each other.
Take Miu Miu, a Prada-owned fashion house. It’s running a literary club that gathers women writers and artists to explore identity, desire, and lived experience through literature, extending the brand into a cultural world that has almost nothing to do with garments and everything to do with what the brand means.
Boot Boyz Biz, a worker cooperative, has turned bootleg t-shirts into a research practice, where every drop comes with a graduate-level essay unpacking the references, and has expanded into a magazine, a design publication, and an online image library, building an entire ecology of knowledge around what could have been a simple streetwear label. Their drops sell out in minutes, because every piece is so densely coded with meaning that if you recognize even a single reference, you’re in.
The same pattern shows up in AI-native companies that understand this. Flora, a creative environment that aggregates 50+ generative models into one canvas, could have positioned itself as a tool. Instead it built a creative practice: an intelligent canvas, a collaborative agent called Fauna, community workflows, a whole environment where ideation, iteration, and production flow together. When a creative team’s entire process runs through Flora, the relationship has moved to the identity level. Switching doesn’t mean finding another tool. It means losing how you think.
Culturally savvy brands, preparing for what’s coming knowingly or unknowingly, are becoming part of how people understand themselves, how they relate to the world, how they want to live and work. That kind of relationship is immune to the agent finding a cheaper alternative, because the value was never in the product. It was in what happened to the person who encountered it. How they started thinking, what they started caring about, the way their life shifted.

In Cultural Codex 01, I’ve mapped these orientations as going broader through worlding cultural worlds, deeper with cultural gravity, and longer through changing lives. Breadth creates surface area for discovery. Depth creates the weight that holds attention. Lasting impact creates relationships that survive any matching function, because they have become part of how someone actually lives
This is what a native entity of the neural era looks like, already visible and successful now. And it is a harder, richer, more interesting thing to build than anything the previous eras demanded.
Build for the market physics that’s coming
Every time the physics of markets has changed, the brands and businesses that thrived were the ones that understood the new physics early enough to build for it rather than react to it.
We are in that window now. The opportunity is two-sided. On one hand, building own agentic plays, developing the interfaces and intelligence layers that will mediate the next era of customer relationships. On the other, doing the deeper work of making the brand and the business genuinely legible, genuinely deep, and genuinely significant in people’s lives. The second part is harder and takes longer. It is also the part that can’t be commoditized once you’ve done it.
Build something real. Make it legible. Give it depth. Make it matter in people’s lives. Go broader, deeper, and longer than the physics of the previous era ever required you to.
The brands and businesses that do this will survive the transition, and define what comes next.
If you’re working on this and want to think it through together, let’s talk.